
- IRS: 2027 HSA and EBHRA Contribution Limits
- DOLTechnicalRelease: Trump Accounts, June 17, 2026
- IRS: Form 5500 Series | U.S. Department of Labor
- IRS: Draft Form & Draft Instructions for Trump Accounts
- Proposed Rule: CMS' Request for Info. re: PBM Compensation & Data Collection
- Resource:Mid-year Paid Family Medical Leave State Chart
- CMS Fact-Sheet: Federal IDROperations Final Rule
- Blog: Why you should review COBRA Notices (even with a vendor)
Compliance Deadlines
- July 31, 2026 – File Form 5500 via DOL’s eFAST2 portal (plans of 100+ participants at beginning of plan year)
- July 31, 2026 – Pay PCORI fee for using IRS Form 720 (self-insured plans)
- September 20, 2026 - Disburse the Summary Annual Report (SAR) to participants (for calendar year plans)
- September 30, 2026 - properly disburse any Medical Loss Ration (MLR) Rebate, as applicable
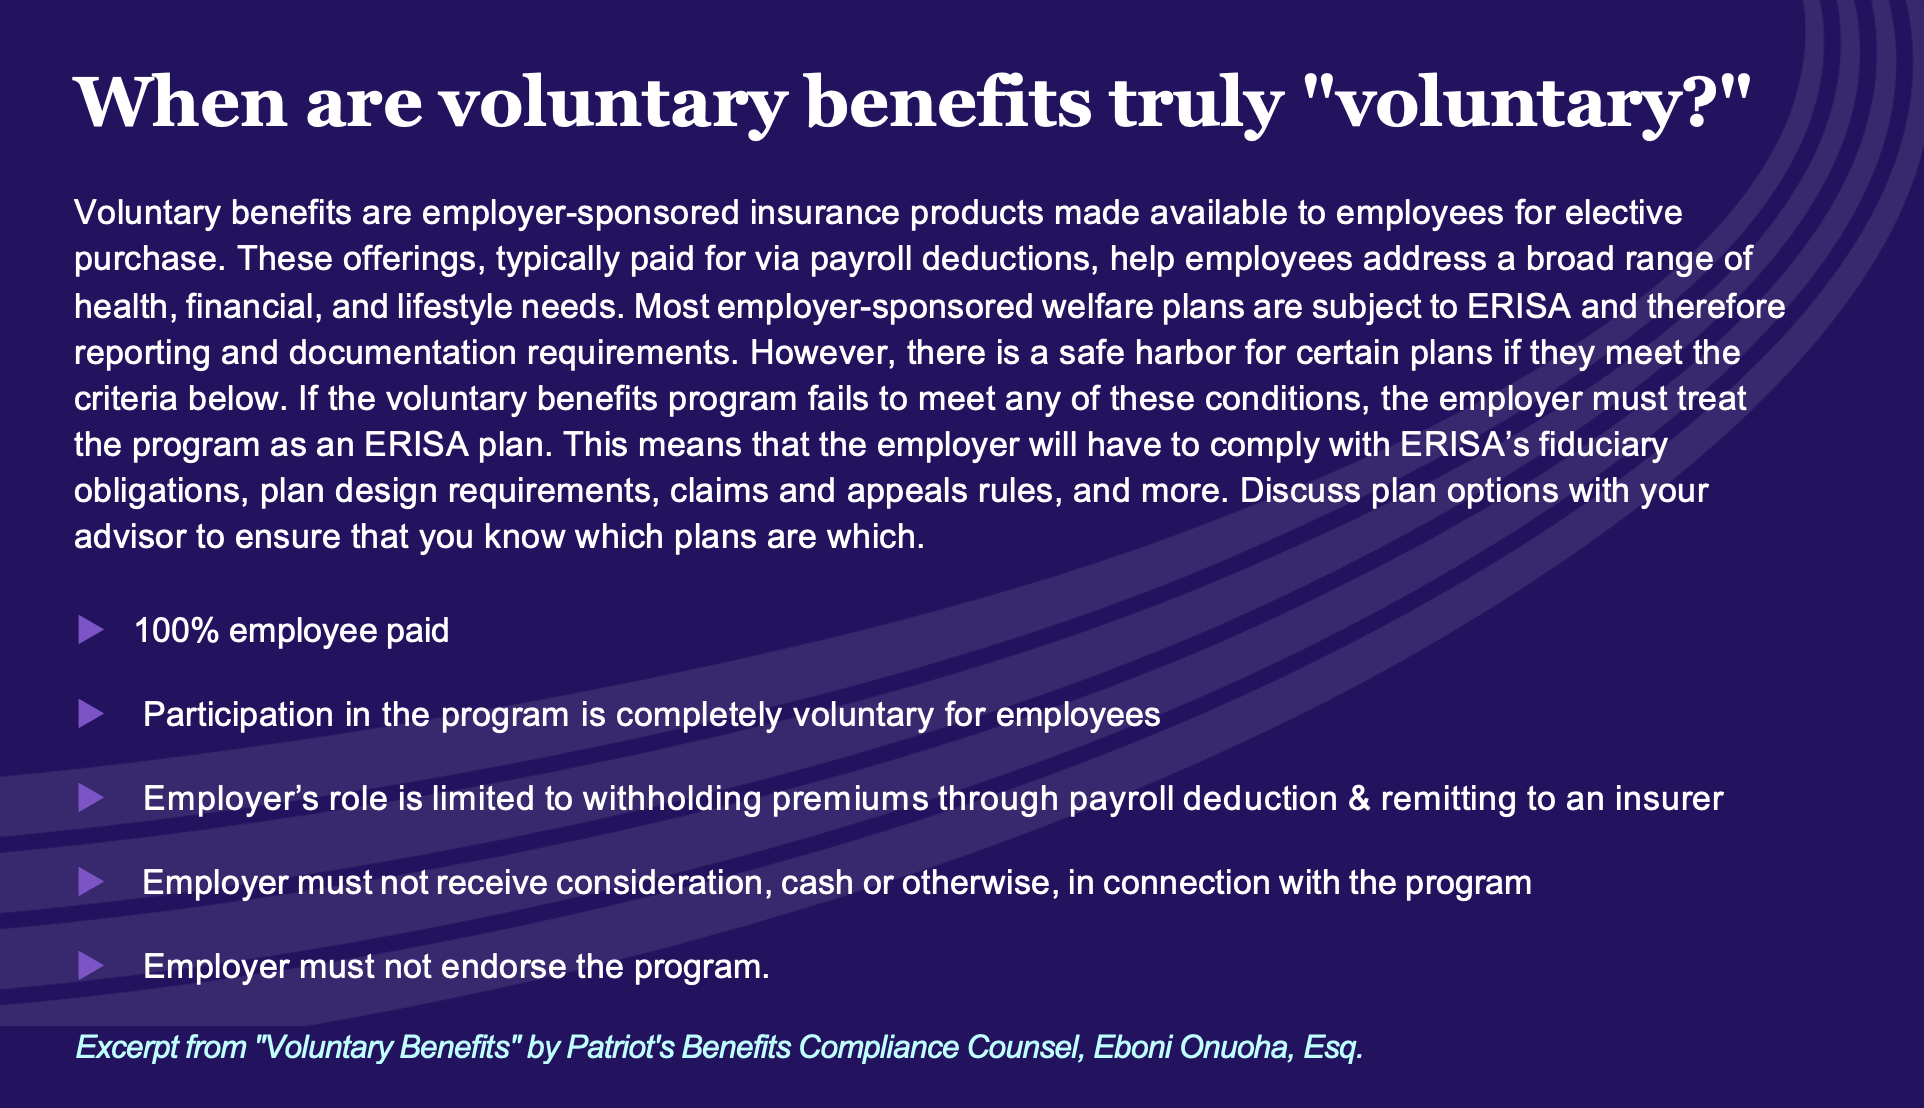
Be weary of some "wellness" or "medical indemnity plans" offering payroll savings
In recent years, several products purporting to offer payroll tax savings for completing a wellness behavior have flooded the market. Such products rely on certain sections of the IRS Code to justify savings. In a nutshell, the employer offers a fixed-indemnity policy under a Section 125 plan, and the insurer pays a “wellness benefit” regardless of the actual medical expense incurred by the employee to offset reduced wages. The IRS, however, says that such fixed indemnity “wellness” payments are taxable wages because they do not reimburse actual medical expenses under Code Section 105. As per the article, watch for these red flags and consult your own tax & legal counsel before implementing such programs:
- Substantial payroll savings for wellness behaviors
- Fixed monthly payments without proof of associated medical expenses
- Reliance on CPT codes in lieu of substantiation
- Legal opinions that do not consider your organization or welfare plan details.
May I require an employee to use PTO before taking unpaid FMLA leave?
- Federal medical leave, the FMLA, permits employers to require employees to use accrued PTO concurrently with unpaid FMLA leave.
- If the employer has a policy in place to permit employees to request to use PTO while on leave, the employee must follow the policy.
- Note that employers must follow their own policies & apply them equitably. If they want to change a policy, it should be prospectively.
- Last, employers must also follow state family & paid leave laws. These may enhance federal leave or restrict the employer from requiring the employee to use accrued PTO. Verify all possible regulation interactions when assessing a leave request. Read the full article here.
About Olivia ‘Liv’ Ash
Olivia “Liv” Ash, Esq., MS, an ERISA attorney, currently serves as AVP, Sr. Benefits Counsel for Patriot Growth Insurance Services, LLC. She holds degrees in Exercise Science, Education, & Law, with Indiana licenses in law & well-being education. Liv supports Patriot’s national suite of advisors regarding federal regulatory compliance as applied to welfare plans. Liv creates content, provides guidance to staff, presents webinars on welfare topics & often speaks at conferences, workshops, & seminars. Liv is a galleried artist; published researcher; & bestselling author in the field of emotional health.
Disclaimer: Content presented is not, nor is it intended to be legal advice; it is for general education purposes. Please consult local legal & tax counsel for specific guidance regarding any one welfare benefits plan. Content is the sole property of Patriot Growth Insurance Services, LLC, and is not to be modified in any way or used for any other purpose. © 2026 Patriot Growth Insurance Services, LLC.